🚨 AI DATA CENTER DEMAND ISN’T THE PROBLEM. THE COST OF CAPITAL IS.
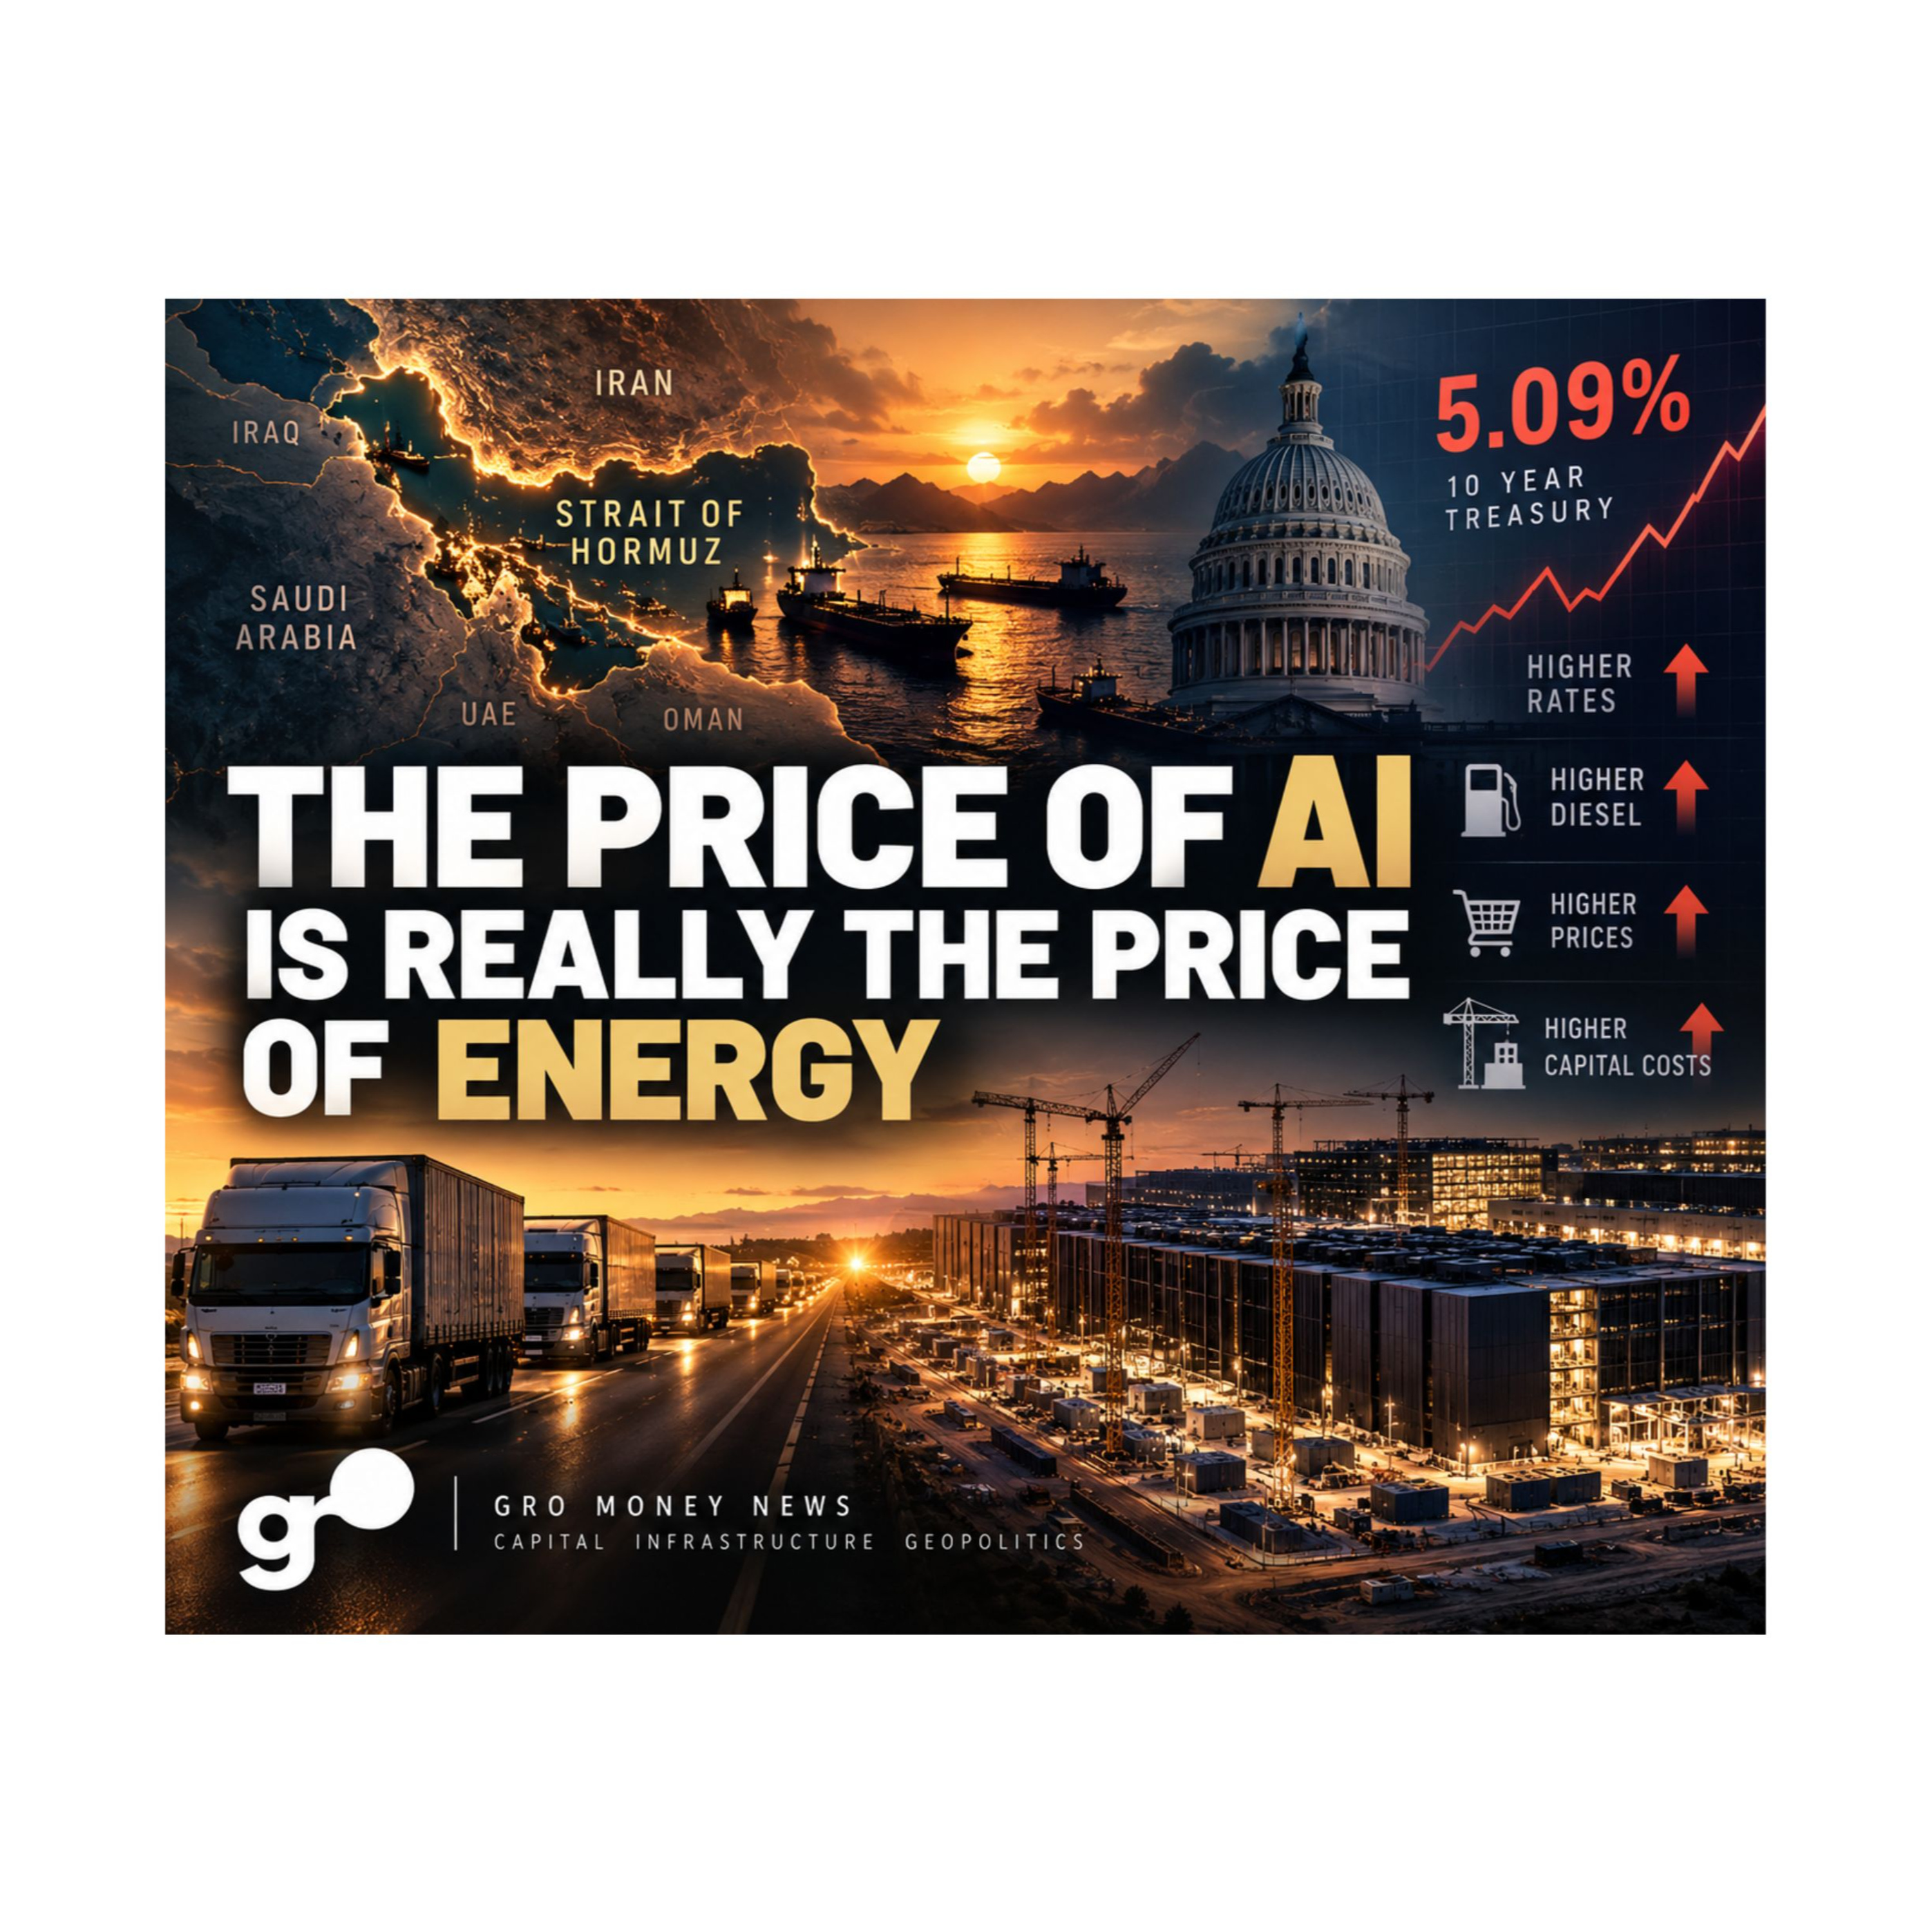
We are heading into a very active Q4 for AI infrastructure, private credit and real assets. CoreWeave is being repriced, Treasury yields remain high, and the market is finally forcing sponsors to prove that projects can survive expensive money.
⛽ The inflation story matters because energy is doing real damage. September CPI was 3.7% year over year, core CPI was 2.6%, gasoline jumped 9.1% in one month, and diesel is roughly 69% higher than a year ago. Using current trucking cost data, that diesel shock alone can translate into roughly a 14% increase in truck operating cost, all else equal.
🚛 Diesel sits underneath the physical economy. Food, construction materials, machinery, consumer goods and data center components all move through logistics, so higher fuel costs eventually become higher operating costs and higher prices.
🌍 This is why the Strait of Hormuz matters to AI finance. Reduce geopolitical pressure, normalize energy flows, cool inflation, ease Treasury yields and the cost of infrastructure capital can fall.
🏭 America also has a structural capacity problem. Smaller refineries have been built and existing facilities expanded, but the last new U.S. refinery with significant downstream processing capacity came online in 1977. We want reshoring, AI, manufacturing and energy security without building enough of the physical infrastructure underneath them.
⚡ My Q4 view is straightforward: the AI infrastructure boom is not dead; indiscriminate capital is. The next two years should reward projects with secured power, credible customers, real offtake, disciplined leverage and capital structures that can actually survive underwriting.
Until tomorrow, be the best human you can be.
~ Teresa Grobecker
#AI #DataCenters #Infrastructure #CapitalMarkets #PrivateCredit #Energy #Inflation
- Duration
- 15m
- Broadcast on
- 18 Oct 2026
- Audio Format
- other
Transcription truncated.
We are heading into a very active Q4 for AI infrastructure, private credit and real assets. CoreWeave is being repriced, Treasury yields remain high, and the market is finally forcing sponsors to prove that projects can survive expensive money.
⛽ The inflation story matters because energy is doing real damage. September CPI was 3.7% year over year, core CPI was 2.6%, gasoline jumped 9.1% in one month, and diesel is roughly 69% higher than a year ago. Using current trucking cost data, that diesel shock alone can translate into roughly a 14% increase in truck operating cost, all else equal.
🚛 Diesel sits underneath the physical economy. Food, construction materials, machinery, consumer goods and data center components all move through logistics, so higher fuel costs eventually become higher operating costs and higher prices.
🌍 This is why the Strait of Hormuz matters to AI finance. Reduce geopolitical pressure, normalize energy flows, cool inflation, ease Treasury yields and the cost of infrastructure capital can fall.
🏭 America also has a structural capacity problem. Smaller refineries have been built and existing facilities expanded, but the last new U.S. refinery with significant downstream processing capacity came online in 1977. We want reshoring, AI, manufacturing and energy security without building enough of the physical infrastructure underneath them.
⚡ My Q4 view is straightforward: the AI infrastructure boom is not dead; indiscriminate capital is. The next two years should reward projects with secured power, credible customers, real offtake, disciplined leverage and capital structures that can actually survive underwriting.
Until tomorrow, be the best human you can be.
~ Teresa Grobecker
#AI #DataCenters #Infrastructure #CapitalMarkets #PrivateCredit #Energy #Inflation